Offering luxury properties in prime locations across the UK
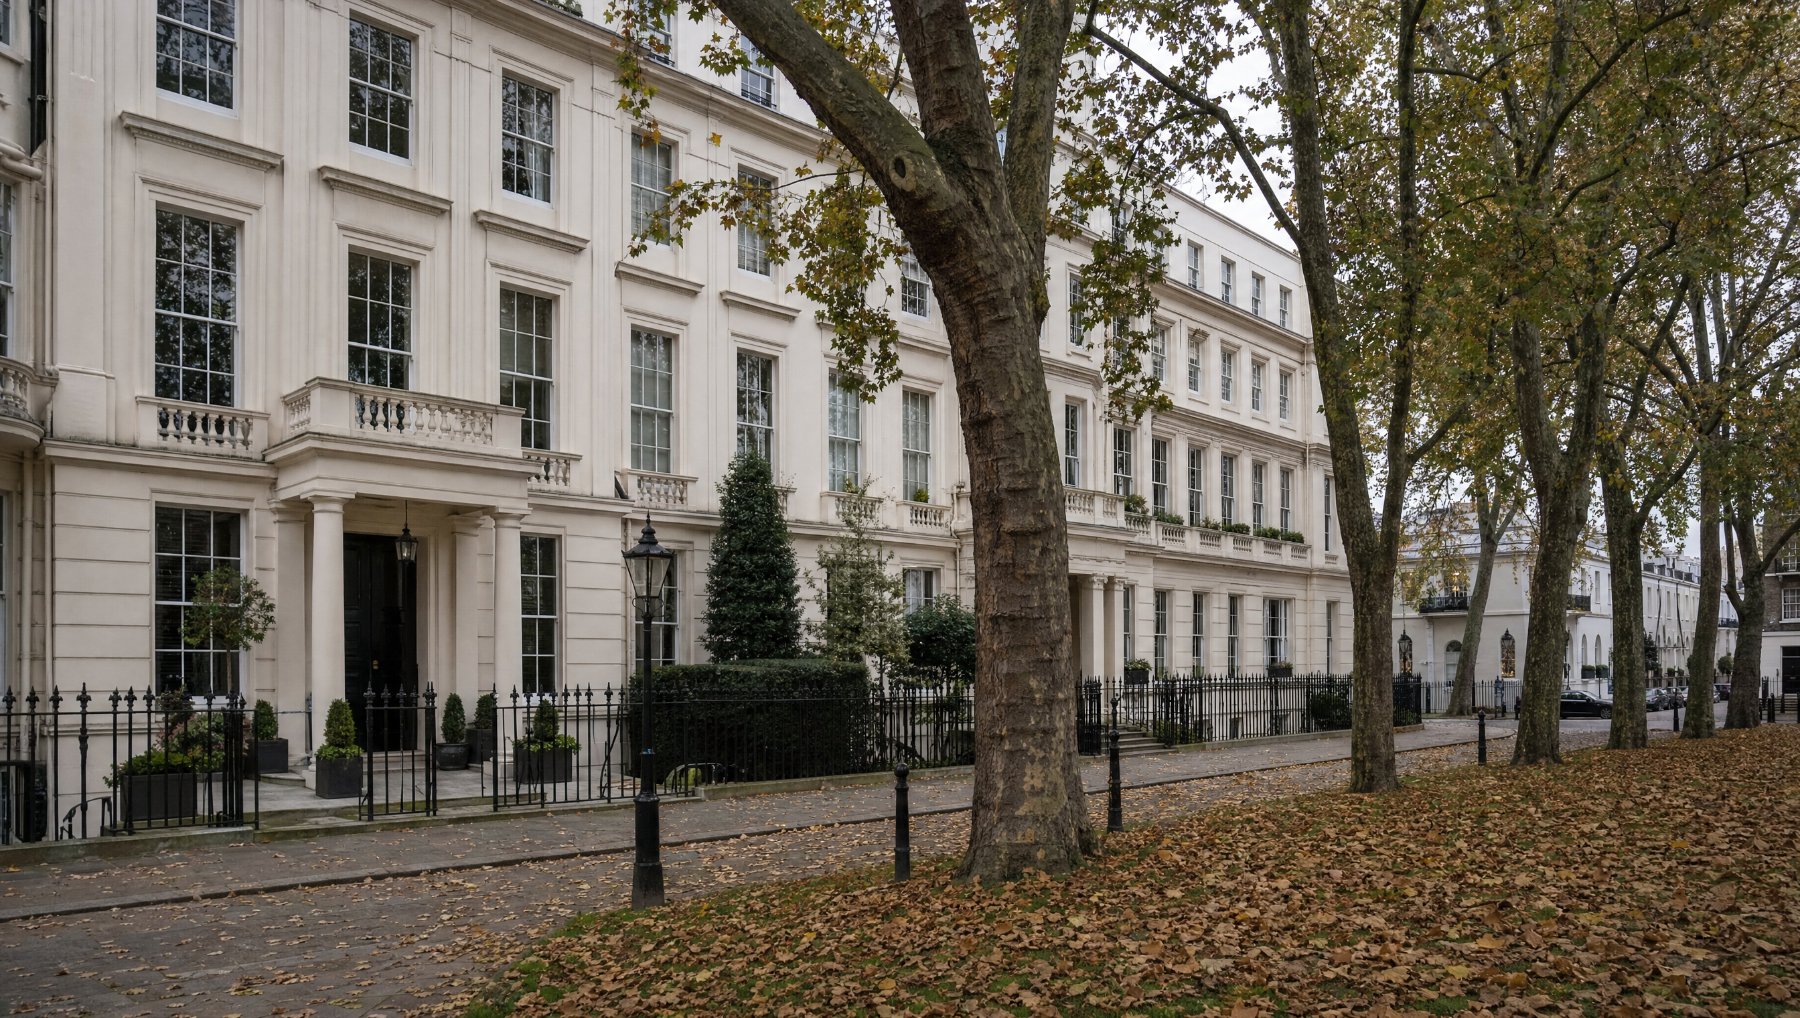
Ten countries account for roughly three quarters of the world’s residential real estate value, and the United Kingdom is one of them. UK property is bought less for yield than for what it is: a transparent title system, a deep and liquid market, and an asset international buyers have treated as a store of value for a very long time.
£272,000
Average price, Jun 2026
2.0%
Annual growth, UK
−2.5%
London, 12 months
None
Residency route
The current market
The average UK house price was about £272,000 in June 2026 — roughly £5,000 higher than a year earlier, an annual rise of 2.0%. This is a provisional ONS and HM Land Registry estimate based on around 47% of the transactions expected for the month, and is likely to be revised.
Annual growth in the twelve months to June 2026 was about 1.8% in England (average £293,000), 2.3% in Scotland (£195,000) and 1.8% in Wales (£213,000). Northern Ireland, measured quarterly, rose 9.2% in the year to Q2 2026, to £202,000.
The national average conceals a market moving in opposite directions. London prices fell 2.5% over the same twelve months — a sustained run of decline. Anyone modelling UK returns on the double-digit growth of 2021–22 is modelling a market that no longer exists. The case for UK property today rests on stability and asset quality, not momentum.
What international buyers need to plan for
Foreign nationals, resident or not, can legally purchase and hold UK property freehold. The complexity is not in the buying — it is in the tax position.
Depending on structure and residence status, exposure can include Stamp Duty Land Tax with a surcharge for non-residents and additional properties, Income Tax on rental profits, Capital Gains Tax on disposal, and Inheritance Tax on UK-situated assets regardless of where the owner is domiciled. That last point catches a great many international owners by surprise, and it is precisely what our estate planning and trust work exists to address.
Speak to an advisor
The tax position, not the purchase, is where UK ownership gets complicated. We structure before you buy.
There is no residency route
The UK — England, Scotland, Wales and Northern Ireland — has no residency-by-property-investment route. Buying UK property confers no immigration status or right of residence, and cannot be used to obtain, extend or settle any visa.
The Tier 1 (Investor) visa closed to new applicants in February 2022 and its remaining provisions have since been removed from the Immigration Rules. Even while it operated, qualifying investment was limited to share or loan capital in active UK trading companies and expressly excluded companies principally engaged in property investment. Be sceptical of anyone who suggests otherwise.
Frequently asked questions
Yes. There is no nationality restriction on ownership and freehold is available to non-residents.
Potentially Stamp Duty Land Tax with non-resident and additional-property surcharges, Income Tax on rental profits, Capital Gains Tax on disposal, and Inheritance Tax on UK-situated assets regardless of domicile. Your exact position depends on residence, domicile and how the property is held.
It depends entirely on what you want from it. Yields are modest and growth is low single-digit, with London currently negative. What UK property offers is a mature, transparent, liquid market in a stable jurisdiction — capital preservation rather than income or momentum.
No. The UK has no residency-by-property-investment route, and property ownership confers no immigration status whatsoever.
Considering the UK?
The purchase is simple. The tax and succession position is not — and it is far cheaper to structure before you buy than to unwind afterwards.